
Agents & automation
Invest System: Quant Research with Agent Review
A rigorous method for stock selection, with a backtest that was not significant.
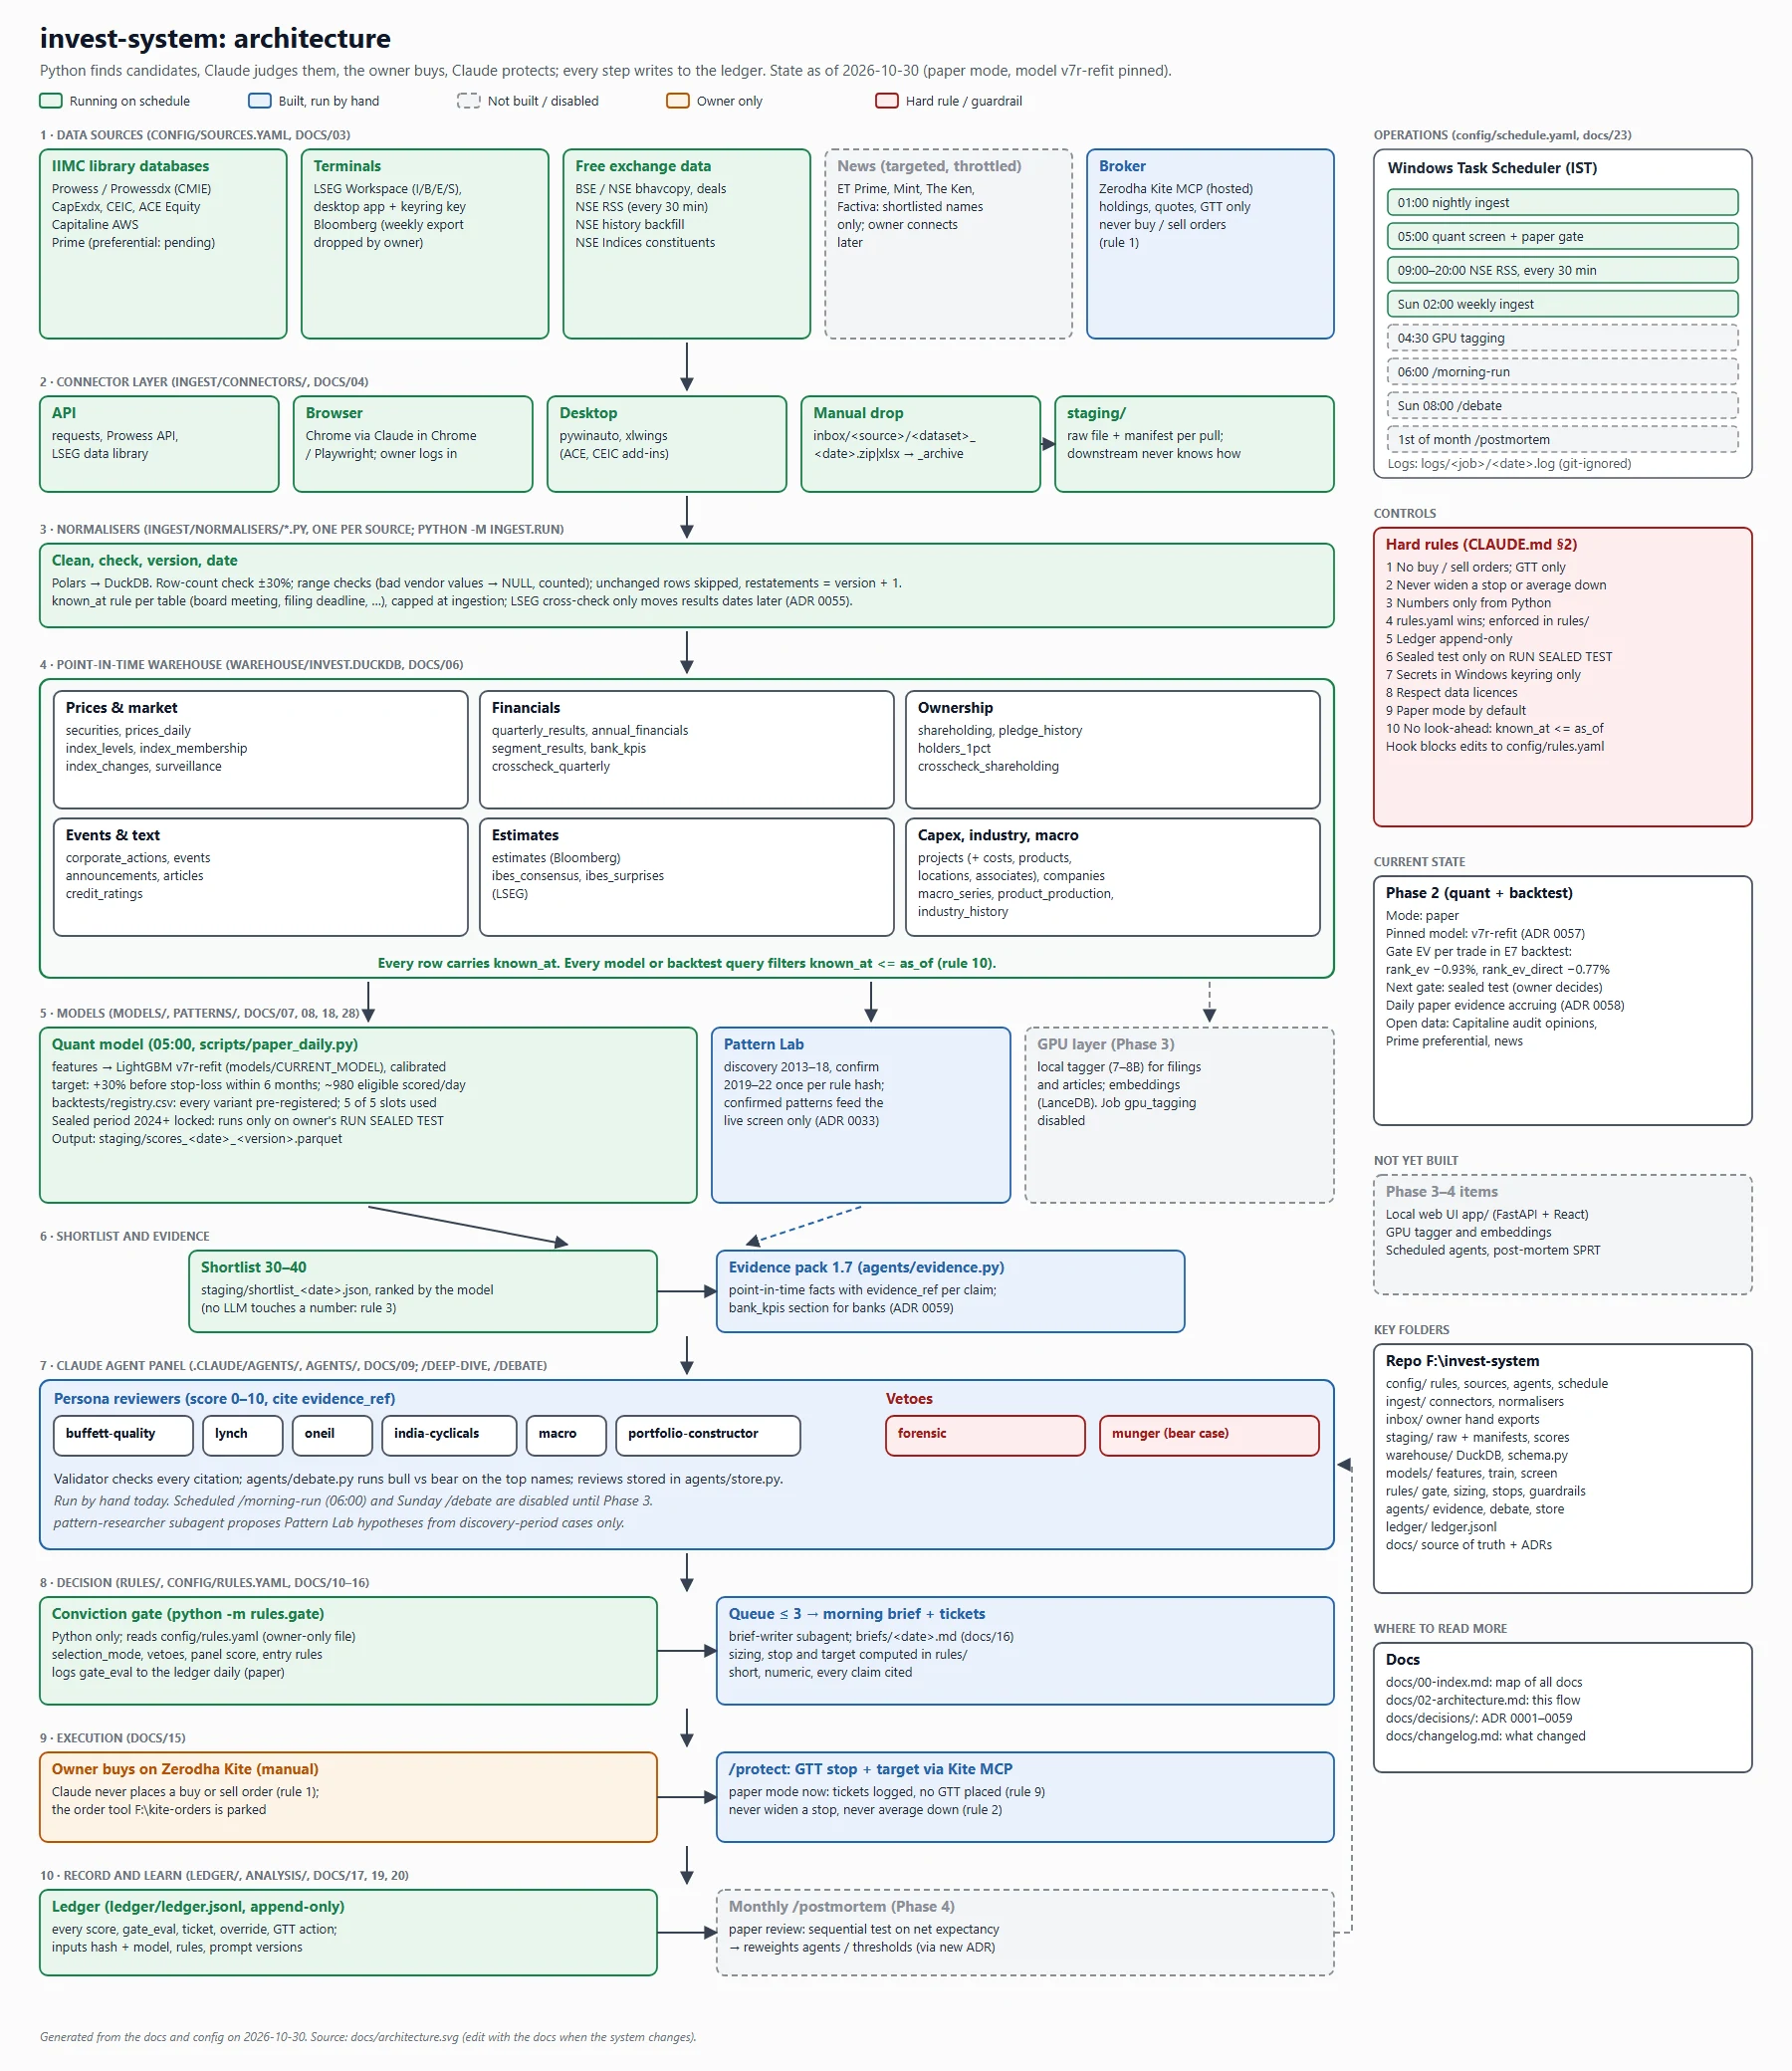
Invest System is a personal research project that estimates, for every Indian listed company, the chance of a large gain before a stop is hit, then has Claude reviewers challenge only a short list. It is strong evidence of method, not of profitability: the backtest was not statistically significant and the system has never traded live.
The problem
The goal is narrow: find at most three high-conviction Indian stocks at a time. For each stock the system estimates the probability of rising 30% before hitting its stop within six months. The hard part is not producing a ranking. It is avoiding the ways a backtest lies: look-ahead, survivorship, and quietly trying many ideas until one works.
This is personal, research-only work. It is not an advisory service, and nothing here is investment advice. I do not publish data, picks or the ledger, and some of the data is licensed under no-redistribution terms.
What I built
A point-in-time warehouse stores every row with a known_at timestamp, so a test can only see what was knowable on the date. It covers 10,049 companies including delisted ones, 13.75 million daily prices from 2010 to 2026, 604 thousand quarterly results and 1.5 million events.
The ranking model is gradient-boosted (LightGBM) with calibration. A sealed out-of-sample period, from 2024 onward, is never touched during development. A hypothesis registry counts every look at the data. A rule engine computes every decision number, and the language model never does. The design has Claude Code subagents, written in the style of different investor philosophies plus forensic and bear-case vetoes, review only the shortlist; that phase is not built yet. The owner buys manually, so the only automated action planned is placing protective stop orders.
This is Claude plus classical machine learning. It is not a small-model system. A local small-model layer for event tagging is designed but I have not confirmed it as built.
How it performed
On the model I pinned, version 7, the information coefficient was +0.23 against -0.10, and it was positive in all 7 years tested. The backtest through the decision gate returned +1.98% per trade at p = 0.12. That is not statistically significant, and I do not treat it as an edge.
Two later variants, v8 and v9, were pre-registered and both failed. Version 7 stays pinned.
The project is only partly built. The data and the model and backtest phases are in progress. The agent review, user interface, paper trading and live phases have not started. The system has never traded live, and no return is recorded.
What I learned
The most useful result was a negative one. Pre-registering v8 and v9, and letting them fail without rescuing them, is what makes the earlier numbers believable. A hypothesis registry feels bureaucratic until you notice how many ideas you would otherwise have tried silently.
A significance test earns its keep by telling you to stop. A p-value of 0.12 on +1.98% is a prompt to collect more evidence, not to start trading.
Letting the language model review a shortlist, and never compute a number that drives a decision, is a division of labour I would reuse. Models are good at argument and bad at arithmetic they are not made to verify.
Method and profitability are different claims. This project supports the first.
More in Agents & automation
- CastLink AutoQuoteReads a drawing from email, checks 49 rules, and drafts a quote for CEO approval.
- The Forge Family: An Agent Operating System on Claude CodeMarketing and research command systems, desktop apps, and a study of AI brand governance.
- Google Ads Agent SystemOne command plans a Search campaign; a human always clicks Publish.